Four accounts run American retirement saving: the 401(k), the IRA, the Roth, and the conversion. They are not four rival products — they are two kinds of account, one tax flavor, and one move between them.
美國人的退休儲蓄,繞著四個名字轉:401(k)、IRA、羅斯(Roth)、轉換(Conversion)。它們不是四種互相競爭的商品——而是兩類帳戶、一種稅務口味、和一個搬錢的動作。
What the Names Stand For
這些名字的由來
401(k) is not a model number. It is a paragraph of the US tax law — subsection 401(k) of the Internal Revenue Code, the part that lets workers set pay aside for retirement.
401(k) 不是產品型號。它是美國稅法裡的一段條文——《國內稅收法典》(Internal Revenue Code) 第 401(k) 小節,就是允許員工把薪水撥出一部分存退休金的那一段。
IRA is short for Individual Retirement Arrangement — the IRS’s official name for a personal retirement account; most people say Individual Retirement Account. And Roth is a person’s name: Senator William Roth, who wrote the Roth IRA into law in 1997.
IRA 是 Individual Retirement Arrangement 的縮寫——這是國稅局給個人退休帳戶的正式名稱;一般人常說 Individual Retirement Account。而 Roth 是一個人名:羅斯參議員(William Roth),他在 1997 年把羅斯 IRA 寫進法律。
The 401(k): Saving at Work
401(k):在公司存錢
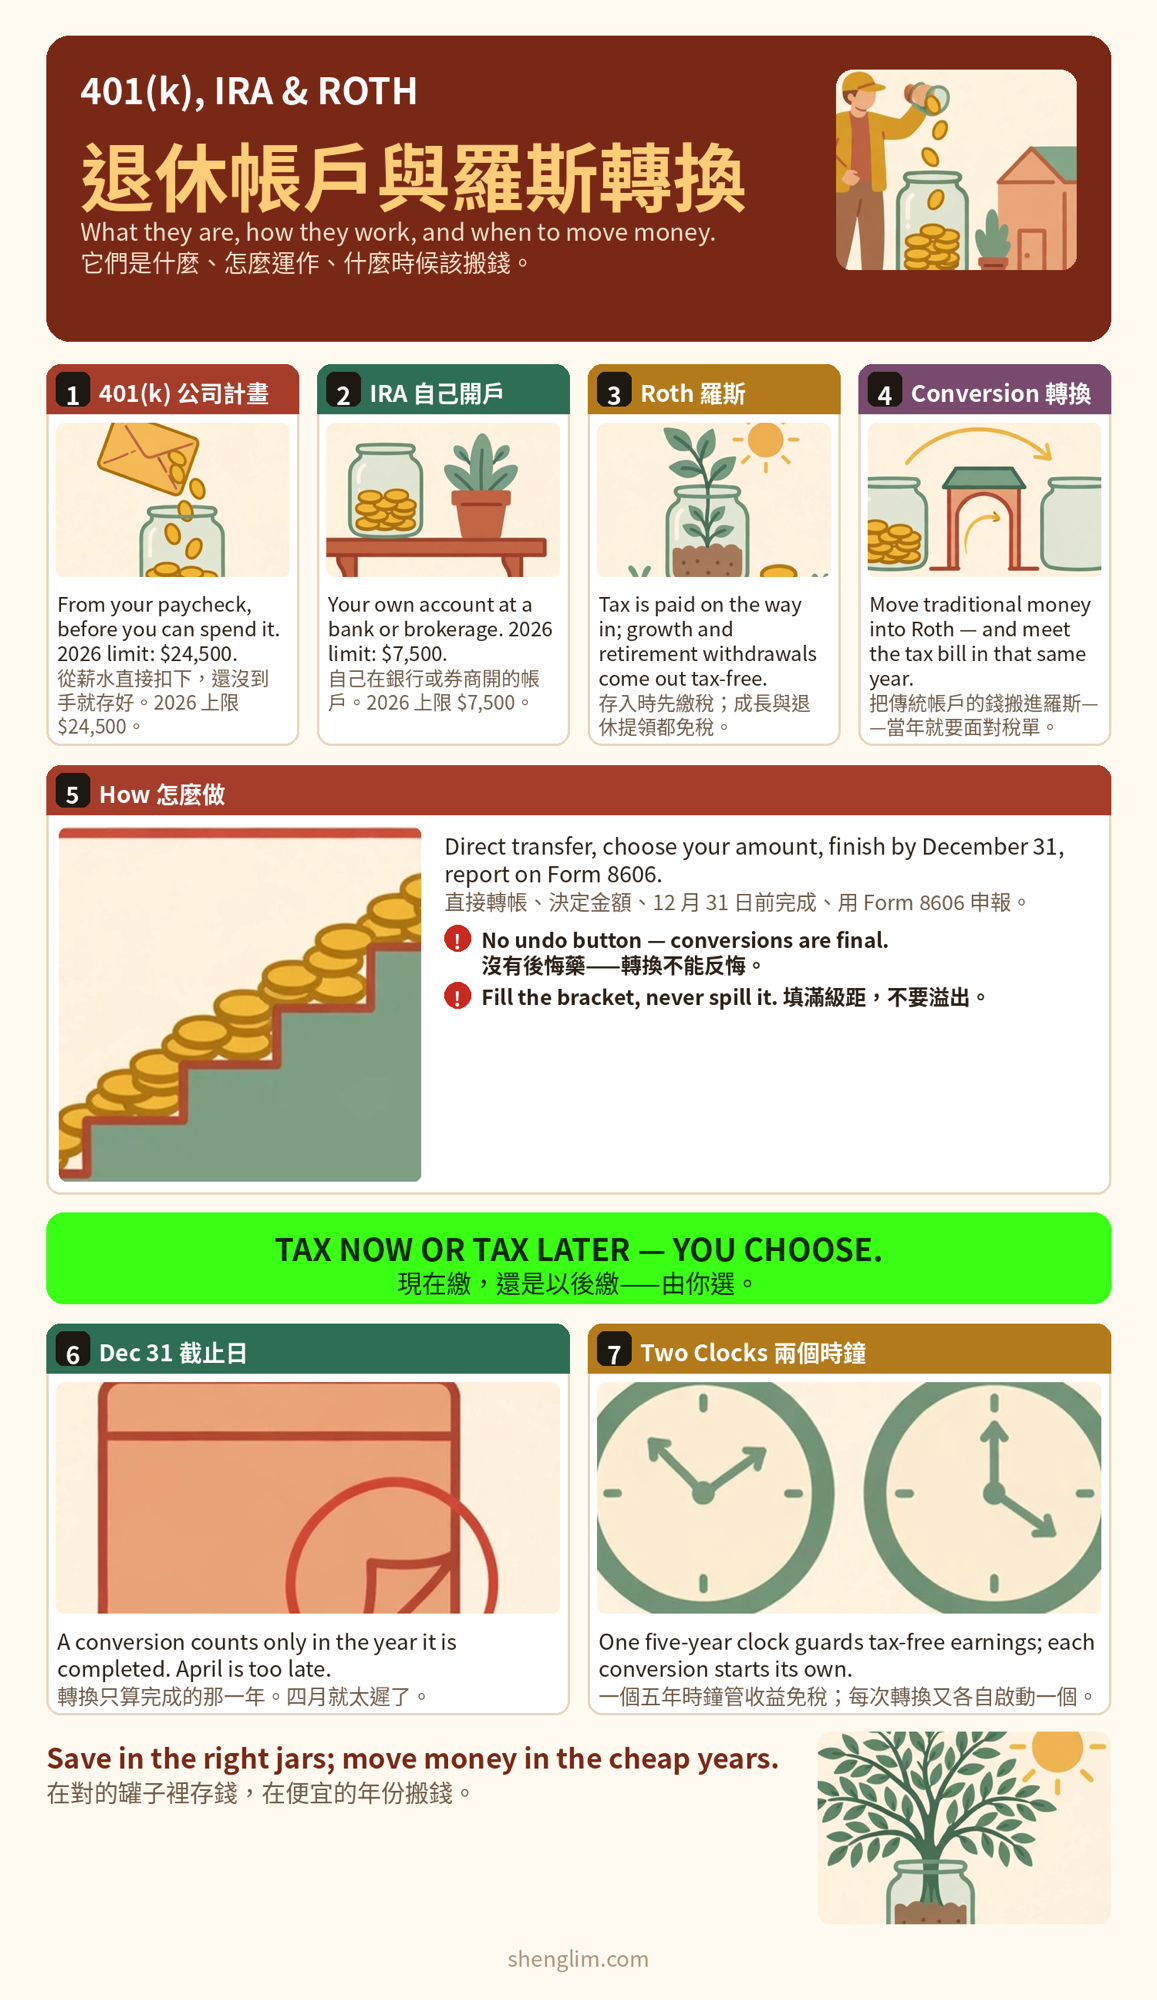
A 401(k) is a retirement plan run by your employer. The money leaves your paycheck before you can spend it — saving on autopilot.
401(k) 是雇主提供的退休計畫。錢從薪水直接扣除,還沒到手就先存好——自動儲蓄。
For 2026 the limit is $24,500; at 50 or older you may add $8,000 more, and at ages 60 to 63, $11,250 more. Many employers add a match — free money; never leave it on the table.
2026 年上限是 24,500 美元;50 歲以上可再多存 8,000,60–63 歲可再多 11,250。許多雇主還會配比(match)——那是免費的錢,千萬不要錯過。
The traditional kind is pre-tax: the tax bill waits until the money comes out, and required minimum distributions (RMDs) start in your seventies. Leave the job, and the money can roll into an IRA.
傳統型是稅前存入:稅單等到提領時才來,七十多歲起要開始強制提領(RMD)。離職後,錢可以轉進 IRA。
The IRA: Your Own Account
IRA:自己的帳戶
An IRA is a retirement account you open yourself at a bank or brokerage — no employer needed. For 2026 the limit is $7,500, plus $1,100 at 50 or older, and you need earned income to contribute.
IRA 是你自己在銀行或券商開的退休帳戶——不需要雇主。2026 年上限 7,500 美元,50 歲以上再加 1,100;存入需要有工作收入。
A traditional IRA works like a traditional 401(k): maybe a deduction going in, tax coming out, RMDs later. It is also where old 401(k)s often end up, gathered in one place.
傳統 IRA 和傳統 401(k) 很像:存入時可能抵稅,提領時繳稅,晚年有 RMD。它也是舊 401(k) 常聚集的地方,集中在一處管理。
Roth: Tax Now, Not Later
羅斯:先繳稅,後免稅
“Roth” is not an account. It is a tax treatment, named after Senator William Roth: money goes in after tax, grows untaxed, and — if the rules are met — comes out tax-free in retirement.
「羅斯」不是一種帳戶,它是一種稅務待遇,以羅斯參議員(William Roth)命名:錢稅後存入、成長免稅,符合規則時,退休提領也免稅。
There is a Roth IRA and a Roth 401(k). Contributing directly to a Roth IRA has income limits; a Roth 401(k) has none. And since 2024, Roth 401(k) money has no RMDs.
有羅斯 IRA,也有羅斯 401(k)。直接存羅斯 IRA 有收入上限;羅斯 401(k) 沒有。2024 年起,羅斯 401(k) 也沒有 RMD。
The bet is simple: pay tax at today’s rate if you expect your retirement rate to be the same or higher — then never owe tax on the growth again.
賭注很簡單:如果你預期退休時的稅率相同或更高,就用今天的稅率先付清——之後的成長,永遠不用再繳稅。
Conversion: Moving to Roth
轉換:搬進羅斯
A Roth conversion moves money from a traditional IRA — or an old 401(k) rolled into one — into a Roth IRA. There is no income limit and no dollar cap, but everything you move becomes taxable income that year.
羅斯轉換,是把傳統 IRA——或轉入 IRA 的舊 401(k)——的錢搬進羅斯 IRA。沒有收入上限、沒有金額上限,但搬過去的每一塊錢,在當年都算應稅收入。
How to do it: ask your brokerage for a direct trustee-to-trustee conversion, choose the amount, and finish before December 31. You will receive a Form 1099-R, and you report the conversion on Form 8606.
怎麼做:請券商做直接轉帳(trustee-to-trustee),決定金額,在 12 月 31 日前完成。之後你會收到 1099-R 表格,並在 Form 8606 上申報這次轉換。
Three warnings. A conversion cannot be undone. The tax is best paid with money outside the IRA, not out of the amount you convert. And if your IRAs hold other pre-tax money, the pro-rata rule taxes every conversion proportionally.
三個警告。第一,轉換不能反悔。第二,稅金最好用 IRA 外面的錢付,不要從轉換金額裡扣。第三,如果 IRA 裡還有其他稅前資金,比例規則(pro-rata rule)會按比例課稅。
Then why convert? The classic window is a low-income year — after retirement, before Social Security and RMDs begin. Convert just enough to fill your current tax bracket, and not a dollar more.
那為什麼要轉?經典時機是低收入的年份——退休之後、社會福利金與 RMD 開始之前。只轉到填滿目前的稅率級距為止,一塊錢都不要多轉。
So run the numbers before you move a dollar. A conversion is income: convert too much in one year and the extra income can push you into a higher tax bracket — and it can also shrink health-insurance subsidies and raise Medicare premiums two years later. Let your tax picture set the amount, not the size of the account.
所以,搬錢之前先把數字算清楚。轉換就是收入:一年轉太多,多出來的收入可能把你推上更高的稅率級距——還可能讓健保補助縮水、讓兩年後的 Medicare 保費變貴。金額由你的稅務狀況決定,不是看帳戶有多大。
Good to Know
須知
Two clocks guard Roth money. Earnings come out tax-free only after the five-year rule and age 59½ (or another qualifying event); and every conversion starts its own five-year clock for the early-withdrawal penalty.
羅斯有兩個時鐘在把關。收益要免稅提領,必須滿足五年規則且年滿 59½(或其他合格事件);每一次轉換,也各自啟動一個五年時鐘,關係到提前提領的罰款。
The dollar limits above are the IRS figures for 2026; they change most years. This post is education, not personal advice — before a conversion of any real size, run your own tax numbers, or sit down with a tax professional.
以上金額是 IRS 的 2026 年數字,幾乎每年都會調整。本文是知識分享,不是個人建議——做金額不小的轉換之前,先算清楚自己的稅,或請稅務專業人士協助。
Let’s Talk About It
來聊一聊
Two coworkers, one lunch break, and the accounts everybody has and nobody understands at first.
兩個同事、一段午休時間,和人人都有、一開始卻沒人搞得懂的帳戶。
Dave: Hey Lisa, quick question — are you putting money into the 401(k) here?
戴夫:嘿,麗莎,快問一下——你有往公司的 401(k) 放錢嗎?
Lisa: Oh yeah. At least enough to get the company match. That’s free money!
麗莎:有啊。至少放到能拿滿公司配比。那是免費的錢!
Dave: Free money? Come on — nothing’s free.
戴夫:免費的錢?拜託——天底下沒有白吃的午餐。
Lisa: Ha — okay, almost free. Don’t grab the match and you’re leaving money on the table.
麗莎:哈——好啦,算是免費。你不拿配比,就是把錢留在桌上不撿。
Dave: Fair enough. My old 401(k) from my last job is just sitting there doing nothing.
戴夫:有道理。我前一份工作的 401(k) 還丟在那裡,什麼事都不做。
Lisa: Roll it into an IRA. Took me twenty minutes online, tops.
麗莎:轉進 IRA 就好。我上網弄,頂多二十分鐘。
Dave: Roth or traditional? Everybody keeps throwing those words around.
戴夫:Roth 還是傳統型?大家一直把這兩個詞掛在嘴邊。
Lisa: Depends. I convert a little to Roth every year — pay the tax now, chill later.
麗莎:看情況。我每年轉一點到 Roth——現在繳稅,以後輕鬆。
Dave: “Chill later” — now that’s a plan I can get behind.
戴夫:「以後輕鬆」——這個計畫,我可以。
Lisa: Just watch your tax bracket. Convert too much at once, and Uncle Sam throws a party.
麗莎:只是要盯著你的稅率級距。一次轉太多,山姆大叔就開派對了。